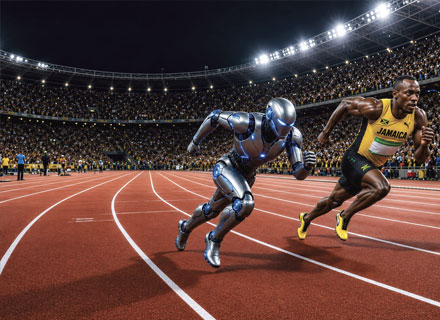

On the evening of August 22, inside the Beijing oval built for the 2022 Winter Olympics, three humanoid robots crouched at the start of a 100-metre lane. A gun fired. Nine and a bit seconds later, a machine called Tianzhuo, built by the Beijing Innovation Centre of Humanoid Robotics, crossed the line a body length clear of the field in 9.39 seconds. Usain Bolt’s world record, set in Berlin in 2009, is 9.58 seconds.
Then Tianzhuo carried on running, because it had no reliable way of stopping, hit a padded barrier, and came apart. Stretcher-bearers carried the pieces away. Bolt, in 2009, jogged a victory lap.
That sequence is the most honest summary of Chinese robotics available anywhere this year. The acceleration is real and it is astonishing. Twelve months earlier, at the first edition of these games, the best 100-metre time was 21.5 seconds. The braking is not there yet.
Which makes the timing of a remark from Wang Xiaogang, chairman of the embodied AI startup ACE Robotics and a co-founder of SenseTime, worth pausing over.
Speaking at the ‘World Robot Conference’ in Beijing the day before the race, he told Reuters he expects to reach the ‘ChatGPT moment’ for embodied intelligence by the end of 2027, driven by world models and the capture of environmental data.
Xiaogang then added the part that rarely survives the headline. Even if that inflection point arrives in late 2027, he said, broad commercial use across sectors is another four or five years beyond.
So, the question for the industry is not whether China is fast. It is whether speed in hardware converts into control of a market that does not yet properly exist.
The shipment numbers are extraordinary, and contested
Counterpoint Research puts global humanoid robot shipments above 22,000 units in the first half of 2026, a rise of nearly 300% year-on-year. Smart Analytics Global counts 19,100 units against 5,100 a year earlier, a 272% jump.
Both agree on the important part. Chinese vendors accounted for more than 97% of global shipments, and China itself represented more than 85% of global demand.
Shanghai-based AgiBot has taken the lead from Unitree, shipping somewhere between 8,400 and 9,700 units depending on whose ledger you trust, for a global share of roughly 44%. Unitree follows with about 5,900 units and 31%.
Between them, two Chinese firms account for three-quarters of every humanoid robot shipped on Earth. Add Galbot, UBTech, and Leju, and the top five control 86% of the category. Four of the five are Chinese, and the fifth is also Chinese.
There is one number worth treating with care. Counterpoint reports that entertainment, performance, data production, and research still account for more than 60% of shipments, with intelligent manufacturing at 13%, and warehousing and logistics at 5%. Smart Analytics Global says industrial and commercial applications are already above 70%.
Those two claims cannot both be true, and the gap is not a rounding error. Part of the explanation is that state-backed training centres in China buy robots in volume purely to harvest movement data, which shows up as a sale and as a deployment without a customer having found a use for the machine. When an industry’s own trackers disagree by this margin about what the robots are for, the shipment totals should be read as a measure of production capability rather than of demand.
The revenue attached to all this remains small. The whole humanoid market is worth roughly $2 billion to $3bn today. Full-year 2026 shipments are forecast at 50,000 to 60,000 units globally, generating perhaps $1.6 billion, though the Humanoid Robot Scene Application Alliance expects Chinese shipments alone to exceed 85,000 against domestic capacity above 100,000 units. That last pairing is the one to watch, because capacity running ahead of shipments is how price wars begin.
Capital has arrived at a speed the sector cannot absorb
Chinese embodied AI companies raised RMB 73.5 billion, about $10.8 billion, across 2025. In the first half of 2026 alone, disclosed funding exceeded RMB 46 billion, roughly $6.39 billion. The first quarter produced 210 financing events worth more than RMB 30 billion, with Shenzhen leading on 44 deals, Beijing on 40, Shanghai on 38, and Hangzhou on 24.
Crunchbase data shows China now accounts for more than 43% of global robotics venture investment. Globally, robotics startups had raised $18.8 billion by July 2026, already ahead of the $15 billion raised across the whole of 2025.
The individual rounds are startling for companies with almost no shipping history. TARS Robotics, one year old, raised a $513 million seed at a $1.9 billion valuation before selling a commercial unit. AI² Robotics raised roughly $735 million at close to $3 billion.
LimX Dynamics took $200 million in a pre-IPO round at $2.21 billion. Galbot closed RMB 2.5 billion with the national AI industry investment fund, Sinopec, and CITIC on the register.
At least 25 Chinese embodied intelligence startups now carry valuations above RMB 10 billion, and 15 of them crossed that line in the first six months of this year.
Then came the listing. Unitree’s Shanghai STAR Market debut on August 19 raised RMB 6.1 billion, about $904 million, for 10% of its enlarged share capital. Nearly 9.8 million retail accounts chased 9.7 million shares.
The stock opened 629% above its offer price, briefly valuing the company at RMB 445 billion, and closed up 460% at a market value near RMB 342 billion.
The average first-day gain for Chinese new listings this year is 279%. Even by the standards of a frothy market, this listing stood out. It did so on a day when the STAR Market Composite fell 7.2%.
Unitree is the sector’s most defensible business. It shipped more than 5,500 humanoids in 2025 on revenue of RMB 1.699 billion, and, unlike almost every peer, it turns a profit.
It is also the company whose first-quarter 2026 net profit fell 52% year-on-year even as its shares were being bid up on the promise of what comes next.
That combination, verified volume alongside compressing margins, is the tension inside the whole Chinese proposition.
Why China got here first, and it is not mainly about robots
China installed 295,000 industrial robots in 2024, some 54% of world installations, and operates more than two million factory robots. The United States installed 34,200 in the same year. That installed base means factories already designed around machines, technicians who know how to maintain them, and buyers who understand the payback maths.
More important is the electric vehicle supply chain. Actuators, the motor and gear assemblies at each joint, are the most expensive and most performance-critical part of a humanoid. Elsewhere in the world they are a bottleneck, because suppliers will not build dedicated high-volume lines for orders measured in dozens, and orders stay small because low-volume components keep prices high.
In the Yangtze River Delta, that deadlock never formed. The precision motors, reducers and sensors that went into China’s EV boom are substantially transferable, and suppliers sit within a two-hour logistics radius of the assemblers.
A prototype that takes twelve weeks in Germany turns around in ten to fourteen days in Shenzhen. Unitree makes its motors, reducers and sensors in-house. UBTech spent RMB 1.67 billion buying control of component maker Fenglong in April to pull actuator supply inside the company.
Beneath that sits raw material. China dominates rare earth processing, and permanent magnets built on neodymium, terbium and dysprosium are what make compact high-torque joint motors possible. Beijing introduced export licencing on several rare earth items in 2025.
In August, Bank of America analysts returning from Beijing concluded that China holds an early lead built on control of both critical materials and downstream manufacturing capacity.
Then there is the state. Embodied intelligence, a term that barely appeared in Chinese policy documents before 2023, now has its own inset box among the top ten new industry tracks in the 15th Five-Year Plan covering 2026 to 2030. That designation unlocks the RMB 60 billion National AI Industry Investment Fund, provincial matching money and a wider trillion-yuan state venture vehicle for AI and emerging technology.
The Ministry of Industry and Information Technology set up a humanoid robot standardisation committee in December 2025, and published a national standard system covering the industry’s full lifecycle by March 2026.
China is leading formulation of international standards for elder-care robots. The playbook is the one used in 5G and high-speed rail. Set the domestic standard, build scale on it, then export it as the norm.
Demand is being manufactured too. A joint directive targets 10,000 commercial humanoids in use by the end of 2026, and the MIIT action plan aims at 100,000 deployed units by 2027.
Shanghai subsidises up to 30% of project costs, and offers compute vouchers. Shenzhen offers up to RMB 100 million for approved special projects.
Unitree’s own prospectus discloses RMB 76 million in tax incentives in the first nine months of 2025, and RMB 32 million in direct government grants since 2022.
This is industrial policy operating on the supply side, the demand side, and the standards layer simultaneously. Nothing comparable exists in the United States or Europe.
The brain is the part China has not bought
Everything described so far concerns bodies. What determines whether humanoids become a large industry or an expensive novelty is whether they can do useful work in places nobody prepared for them. That is a software problem, and by the admission of the people building these machines, it is unsolved.
Wang Xiaogang’s late-2027 forecast is the optimistic end of the range. Wang Xingxing, Unitree’s founder, said in the same week that a dramatic breakthrough in robot brains is two to three years away at the earliest. Both men point to the same bottleneck, which is high-quality real-world training data.
Language models had the internet. Robots have no equivalent corpus, because the data has to be generated by machines physically doing things and failing.
ACE Robotics aims to collect tens of millions of hours within two years, and plans deployments across 1,000 stores. That is the shape of the race now, not the sprint track.
The dependency question cuts against China here. Its embodied AI sector still leans heavily on Nvidia chips and the surrounding software ecosystem, even as the hardware supply chain localises rapidly.
And the frontier of world models is genuinely contested. Alibaba’s Qwen-Robot Suite, ByteDance’s world model programme, and a wave of Chinese vision-language-action architectures sit alongside American and European efforts that have more verified operating hours in commercial settings.
That last point deserves weight. Figure AI’s robots at BMW’s Spartanburg plant have logged more than 1,250 hours loading sheet-metal parts, handling over 90,000 components at better than 99% placement accuracy.
It is a small deployment, but it is audited, paid for by a customer, and productive. Tesla, meanwhile, has slipped Optimus production milestones repeatedly and had no external deployments as of mid-2026, despite committing $20 billion of capital expenditure this year.
UBTech’s Walker S2 has 1,079 audited unit sales in 2025, and contracts with Foxconn, BYD and Audi FAW, and the company expects humanoids to exceed 80% of its revenue in 2026, though it remains loss-making and lifted its Walker S delivery guidance to 5,000 units only after previously guiding to 2,000.
Nobody, anywhere, has deployed humanoids above the low hundreds of units in a sustained commercial environment. The Chinese lead is a lead in production, not in usefulness.
The wall that Washington built
On July 28, the US Federal Communications Commission added foreign-produced humanoid and quadruped robots, along with power inverters, to its Covered List. The practical effect is that new device models cannot obtain the equipment authorisation almost every electronic product needs before it can be imported, marketed, or sold in the United States.
Models already authorised are unaffected, federal government use is exempt, and producers can seek conditional approval through the Department of War.
Chairman Brendan Carr framed the move as an effort to secure America’s critical supply chains. The commission insists the action is country neutral, and turns on place of production rather than ownership.
Nobody is fooled by the framing. China holds roughly 85% of the global humanoid market, and Beijing’s foreign ministry said it would take all measures necessary to defend Chinese firms, calling the restrictions protectionism.
Running in parallel is a Commerce Department Section 232 national security investigation into imports of robotics and industrial machinery, opened in September 2025, and explicitly covering parts and components. Previous Section 232 actions under this administration produced 50% tariffs on steel, aluminium and copper derivatives, and 25% on vehicles and parts.
Here is the strategic wrinkle. Because more than 85% of humanoid demand is currently Chinese, the ban does less immediate damage than it appears to. What it does is foreclose the future.
AgiBot already has deployments live in the United Kingdom and Germany. The American market, the one Morgan Stanley expects to hold 77.7 million humanoids by 2050 against 302.3 million in China, is being walled off before Chinese firms could reach it. Disruption requires access to the market being disrupted.
The involution problem
The domestic market has its own hazard, and Chinese founders name it themselves. By MIIT’s count, China had more than 140 humanoid manufacturers and over 330 products by the end of 2025.
Executives at AgiBot have publicly warned that the industry is already showing signs of involution, the self-destructive price competition that hollowed out margins across the EV sector, particularly in semi-humanoid and entertainment machines where barriers are low and prices are falling fast.
Chinese carmakers, fresh from their own price war, are pouring into embodied intelligence and repurposing factories for it.
Most of the 25 startups now valued above RMB 10 billion carry cash runways of 18 to 24 months. That is the clock. Consolidation, down rounds and outright failures are the arithmetic consequence of 15 companies reaching billion-dollar-plus valuations in a single half-year while the entire global category generates under $2 billion of revenue.
Valuation compounds it. Unitree’s first-day close implied a multiple in the region of 200 times its 2025 revenue. That price only makes sense if the ChatGPT moment arrives roughly on Wang Xiaogang’s schedule, and the commercial ramp behind it arrives faster than he himself expects.
If the breakthrough slips to Wang Xingxing’s two-to-three-year horizon, or if it lands and useful deployment still takes another four or five years after that, a lot of Chinese paper wealth has been created against a revenue line that will not appear inside the average fund’s holding period.
So, disruptor or not
On manufacturing and cost, China has already disrupted the industry and the outcome is not in serious doubt. It sets the price floor, it owns the component base, it controls the magnet supply, and its 97% shipment share reflects a structural advantage built over two decades in electronics and EVs that no rival can replicate quickly. Unitree’s G1 sells at RMB 99,000 against Western full-size platforms that cost an order of magnitude more.
On intelligence, the outcome is open. The world model race is early, the data bottleneck is universal, and the most credible verified deployments to date belong to an American firm working inside a German carmaker’s plant. Chinese executives are the ones saying this most plainly.
On markets, China is being contained in real time, and the containment is arriving before the product is ready. That is unusual. Export controls normally chase a mature industry. This time, the wall went up while the robots were still falling over.
The honest reading is that China has won the phase of this industry that rewards building things, but the phase that decides who captures the value has not started.
Watch three things over the next eighteen months. Whether the entertainment and research share of shipments falls decisively below half, which would show real demand replacing subsidised demand.
Whether any Chinese firm publishes audited operating hours from a paying industrial customer at the level Figure has. And, whether the first serious down round lands in that cohort of 25 unicorns.
The robot beat Bolt. It could not stop, turn, or walk off the track. Both facts are the story.