
Nigerian stock exchange (NGX), from fighting demons like foreign-exchange uncertainty, shallow liquidity, uneven policy transmission, and difficulty in converting local currency returns into reliable dollar outcomes, has achieved a tremendous feat by becoming the best-performing equity market globally in dollar terms in 2026, with a 67% return.
Also, S&P Dow Jones Indices recently suggested upgrading Nigeria to frontier market status, a news that will sound like a music in the ears of investors searching for emerging markets to make their money work.
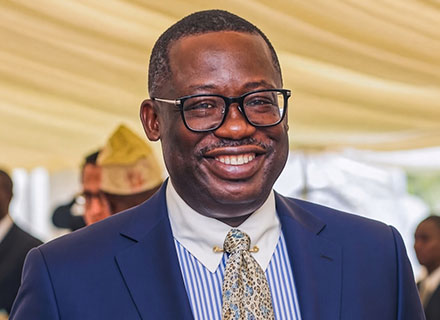
To know more about the NGX’s bull run, International Finance caught up with Hon. Dele Kelvin Oye, who serves as the Chairman of two key bodies: Alliance for Economic Research and Ethics LTDGTE and the Nigeria–Turkiye Business Council. Kelvin Oye talked in detail about the various facets of the stock market uptick, including the key sectors driving the rally, the key numbers and data that everyone should take note from the bull run and most importantly, how the Bola Tinubu administration’s reform drive helped in Nigeria earning the investor confidence.
Here the excerpts from the interview.
With a 67% return, Nigeria’s stock market has been the best-performing equity market globally in dollar terms in 2026. What have been the key factors driving the rally?
Three years ago, many investors would have regarded a sustained Nigerian equity-market rally as improbable. Nigeria was widely associated with frontier-market risk: foreign-exchange uncertainty, shallow liquidity, uneven policy transmission, and difficulty in converting local currency returns into reliable dollar outcomes. That scepticism was not irrational. It reflected real institutional and macroeconomic constraints.
The important point today is not that those constraints have disappeared. It is that the direction of travel has changed. Nigeria’s equity market has responded to a combination of reform expectations, bank recapitalisation, improved foreign-exchange liquidity, stronger market infrastructure, corporate capital raising, and renewed interest in the Nigeria’s long-term productive capacity. NGX reported, citing Bloomberg data across 92 global exchanges, that Nigeria’s benchmark equity index had delivered a 67% return in US-dollar terms since the beginning of 2026, narrowly ahead of South Korea’s KOSPI at 66%. That is an extraordinary dated observation. It should be respected, but not romanticised.
A market rally is not a referendum on one policy or one administration. It is a forward-looking aggregation of expectations about earnings, liquidity, currency, interest rates, commodity prices, governance, and political risk. The Nigerian Exchange is therefore pricing both improvement and uncertainty. The task before policymakers and market institutions is to convert a powerful repricing into durable capital formation.
The reform programme began with difficult decisions, including the removal of the petrol subsidy and the movement toward a more unified, market-based foreign-exchange regime. The social costs have been substantial, and responsible economic leadership must acknowledge them. The IMF’s 2026 assessment recognised improved macroeconomic resilience while also warning that poverty and food insecurity remained severe. Stability that is not eventually translated into lower living costs, employment, energy reliability, and wider opportunity will not possess enduring legitimacy.
At the Alliance for Economic Research and Ethics, we view the current market through four lenses: the strengthening of bank balance sheets, the arrival and prospective arrival of strategic issuers, the interaction between currency conditions and asset prices, and the continuing influence of oil and gas on Nigeria’s external and fiscal position. These are not guarantees of perpetual appreciation. They are the principal mechanisms through which reform expectations are being transmitted into market prices.
S&P Dow Jones Indices has suggested upgrading Nigeria to frontier market status. How do you view this development?
S&P Dow Jones Indices’ decision to place Nigeria on its 2027 Country Classification Watchlist is significant, but the language must be precise. Nigeria is being considered for possible reclassification from Standalone Market to Frontier Market; this is not an upgrade from an existing frontier classification.
The distinction matters because index classification is not a ceremonial label. It affects how global investors define their investable universe, how benchmark providers construct portfolios, and how asset owners assess operational accessibility.
A possible reclassification would signal that Nigeria’s market infrastructure, regulatory environment, transparency, enforcement, and accessibility are moving closer to the requirements of a recognised frontier-market universe. It would not, by itself, create sustainable foreign inflows.
Nor should we confuse a watchlist with a completed decision. S&P DJI has indicated that consistent policy implementation and operational resilience will be important to the review. The appropriate Nigerian response is neither triumphalism nor defensiveness.
It is to keep improving the practical experience of investing: timely settlement, reliable price discovery, predictable regulation, credible enforcement, transparent corporate actions, and efficient repatriation through authorised channels.
The broader lesson is that market credibility is accumulated through repetition. One successful transaction is encouraging; a decade of consistent execution is transformative.
Please tell our readers about some of the sectors that have driven the NGX’s bull run.
The rally has involved more than one sector, but it has not been evenly distributed. The available H1 2026 data show a market that is broad in direction and concentrated in leadership and magnitude. BusinessDay newspaper, citing NGX index performance, reported H1 gains of approximately 90.2% for Oil & Gas and 79.0% for Industrial Goods. The NGX’s weekly report for the period ended June 26 2026 recorded broadly similar year-to-date figures.
Banking has also been a major contributor. The CBN’s recapitalisation framework requires minimum capital of ₦500 billion naira for commercial banks with international authorisation, ₦200 billion naira for national banks, and ₦50 billion naira for regional banks. The exercise has encouraged banks to raise equity, strengthen their balance sheets, reassess their strategic scale, and prepare for a more competitive regional environment.
NGX reported that Nigerian banks raised and listed an estimated ₦2.25 trillion naira in 2025. Total NGX listings were estimated at ₦6.34 trillion naira, including ₦3.79 trillion naira in Federal Government bonds and ₦299.69 billion naira in other corporate listings. These figures are evidence of a more active primary market. They are not, by themselves, proof that every new issue will create value or that the secondary market has become deep enough for all investors.
Consumer Goods also gained, although more modestly, while the Insurance sector was negative in the NGX report accessed for the period. It is therefore more accurate to say that the market has experienced meaningful sectoral participation with pronounced leadership from Oil & Gas, Industrial Goods, and selected financial and energy names. The result is impressive, but it should not be described as an evenly distributed, all-sector advance.
This distinction is important for investors and policymakers alike. Breadth of participation matters, but concentration matters too. A market driven by a few large constituents can produce a strong index return while leaving liquidity and valuation risks unresolved elsewhere.
Can you break down some of the key data and numbers behind the NGX’s valuation rise in 2026?
The NGX All-Share Index closed at approximately 74,800 points at the end of 2023 and stood at 245,209.34 points on August 6 2026 according to market-data reports. The arithmetic implies a nominal naira index increase of approximately 227.8% over that interval. That is an extraordinary movement, but it is a price-index return, not a claim that the underlying economy or every listed company increased in value by the same amount.
Market capitalisation also rose sharply. Contemporary reports placed it at approximately ₦158.3 trillion naira in early August 2026, compared with about ₦30 trillion naira at the end of 2023. Market capitalisation is a valuable measure of the market’s scale, but it is not identical to real wealth creation. It can change because share prices rise, new securities are issued, companies are admitted to the market, corporate actions alter the share count, or the currency and nominal price level change.
The strongest international comparison is the one that is explicitly dated and denominated. NGX reported that the benchmark delivered 67% in US-dollar terms since the start of 2026, ahead of South Korea’s KOSPI at 66% in the Bloomberg comparison cited by NGX. Naira returns and dollar returns answer different questions. A domestic investor experiences the local-currency return; an international investor also experiences the movement of the naira against the dollar.
Liquidity deserves the same precision. NGX reported that banks and other issuers contributed materially to the ₦6.34 trillion-naira of 2025 listings, while the broader market’s daily trading depth remains a separate question. A larger market is not automatically a liquid market. Liquidity is the capacity to transact meaningful size at reasonable cost, with dependable two-way prices and without materially moving the market.
The proper conclusion is therefore measured: the rally has been substantial, participation has widened, and primary-market activity has strengthened, but the durability of the repricing will ultimately be tested by earnings, free cash flow, governance, valuation, and the ability to trade and repatriate capital under pressure.
Since the beginning of 2026, the naira has strengthened by about 4% against the US dollar, amplifying returns for international investors. How do you read the currency’s renewed strength and the NGX’s meteoric rise?
The naira and the NGX have moved in a relationship that deserves careful analysis. When the currency is volatile, a foreign investor may make a profit in naira and still lose money in dollars. That possibility creates what can be described as confidence deficit. The movement toward a more market-based FX regime has therefore been important, even though it has not eliminated liquidity, documentation, or execution risks.
NGX reported an approximate 4% appreciation of the naira against the US dollar since January in the context of its July 2026 market report. The IMF, using a different comparison period, reported a 10% year-on-year appreciation against the dollar in March 2026. These figures are not necessarily inconsistent; they measure different intervals and may use different reference points. A responsible speaker must always state the date range and exchange-rate basis.
A currency can influence equity performance through several channels. It affects the translated value of hard-currency earnings, the naira value of foreign assets and liabilities, import costs, interest-rate expectations, and the willingness of international investors to hold local securities. It can also produce accounting gains that are not the same as recurring operating earnings. That is why FX revaluation gains should never be treated as a substitute for durable business performance.
The IMF has rightly welcomed the Nigerian government’s commitment to a flexible exchange-rate regime while continuing to call for the reduction of remaining exchange restrictions, capital-flow measures, and multiple-currency practices as conditions permit. The mature position is neither to deny progress nor to claim completion. Nigeria has moved in the direction of a more unified market-based system; the work of building deep, predictable, and trusted FX liquidity continues.
The naira’s depreciation created a powerful incentive for foreign investors to seek inflation hedges in equities. Can you elaborate further on this dynamic?
Currency depreciation can encourage investors to seek assets with pricing power, inflation protection, or hard-currency earnings. In Nigeria, companies with export exposure, regulated pricing, strong brands, or the ability to reprice products may be perceived as better positioned than businesses whose revenues are fixed in naira while their costs are imported.
But this mechanism must not be presented as a universal law. Depreciation can also weaken household purchasing power, increase working-capital requirements, raise debt-service burdens, and reduce the real value of domestic savings. In banks, FX movements can generate large reported gains or losses that may not recur. In consumer businesses, the ability to pass on costs depends on demand, competition, and the consumer’s capacity to pay.
The more defensible conclusion is that depreciation may redirect capital toward selected equities, especially where investors perceive a hedge against inflation or currency weakness. It does not make equities immune to macroeconomic damage. If currency deterioration becomes disorderly, the market’s valuation, financing conditions, and earnings quality can all suffer.
For the next phase, returns must increasingly be earned through revenue growth, productivity, stronger balance sheets, dividends, and disciplined capital allocation. The depreciation trade is not a development strategy. It is, at most, a transitional feature of a market adjusting to a new nominal environment.
How much have the government reforms contributed to the NGX’s bull run, and how important have they been in restoring investor confidence?
President Tinubu’s reforms have been important to the market’s change in direction, but it would be too simple to attribute the entire rally to one administration or one announcement. Investor confidence is built through a chain of expectations: the belief that prices are becoming more transparent, that contracts will be respected, that capital can be moved through lawful channels, that financial institutions are resilient, and that policy will be implemented consistently/predictably.
The Central Bank of Nigeria (CBN) states that Nigeria moved toward a new foreign-exchange framework in June 2023, including a willing-buyer, willing-seller model. This was a significant policy shift. It should not, however, be described as a guarantee of a permanently single exchange rate or frictionless access to dollars. The IMF’s 2026 assessment continued to identify remaining exchange restrictions and multiple-currency practices as matters for further reform.
The same principle applies to fiscal reform. President Tinubu assented to four tax-reform Acts on June 26 2025, with the principal provisions scheduled to commence on January 1 2026. That is a consequential legislative achievement. Yet enactment is not the same as successful implementation. The credibility of Nigeria’s tax reform will depend on administrative clarity, institutional capacity, taxpayer confidence, and the quality of public expenditure.
The market does not require government to promise perfection. It requires government to demonstrate a credible process: explain the objective, publish the rules, apply them fairly, measure the results, and correct errors without destroying predictability. That is the foundation of a genuine credibility dividend.
The NGX is also eagerly awaiting the listing of Dangote Petroleum Refinery. Do you see the listing creating another bull run in the Nigerian equities market?
A potential listing of Dangote Petroleum Refinery could become an important event for Nigeria’s capital market. It would bring a large strategic industrial asset into the public-market conversation, broaden sectoral representation, create an opportunity for price discovery, and test the NGX’s capacity to support a transaction of global significance.
The word potential is essential. Current reporting points to a proposed offering, but the reported stake, timing, valuation, and proceeds have changed across accounts. Reuters reported in August 2026 that the refinery was aiming to raise $5 billion through a proposed October 2026 listing, following a reported $2.5 billion private placement for a 6% stake that implied a valuation of approximately $40 billion. Those reported terms should not be confused with a final prospectus or approved offer document.
Nor should investors assume that a large listing automatically creates a bull market. The effect would depend on valuation, free float, governance, disclosure, dividend policy, the treatment of foreign-currency earnings, and the ability of local and international investors to trade the shares. Reports of possible dollar-denominated dividends should remain described as a proposed feature until formally documented in the offer materials and approved through the relevant regulatory process.
The strategic significance would nevertheless be considerable. Nigeria needs more large, transparent, productive companies represented in the public market—not only banks and consumer companies, but energy, infrastructure, technology, healthcare, agriculture, and industrial businesses. A successful offering would be valuable not because size alone is virtuous, but because it could establish a higher standard for disclosure, governance, research coverage, and long-term ownership.
Do you see more IPO opportunities arriving at the NGX amid the ongoing bull run? What sectors or companies could potentially drive the next wave of listings?
Nigeria has a credible opportunity to deepen the pipeline of public-market issuers, but the language should be realistic. Energy infrastructure, gas processing, power, agriculture, food manufacturing, healthcare, logistics, and technology all require long-term capital. The NGX can become an important channel for that capital if it continues to improve listing standards, research coverage, settlement, market making, and investor education.
The history of recent listings also teaches us to distinguish between a primary capital raising and a listing by introduction. Geregu Power was admitted to the NGX in October 2022, BUA Foods in January 2022, Transcorp Power in March 2024, and Aradel Holdings in October 2024. Several of these were listings by introduction rather than public offerings that raised new equity at the time of admission.
They listings were still strategically important. They broadened the investable universe, enhanced visibility, improved price discovery, and created a public-market platform that could support future financing. But precision matters. A listing can be a major capital-market event without being a primary IPO.
The next wave will be determined by the willingness of credible companies to accept the disciplines of public ownership: audited reporting, timely disclosure, independent oversight, investor relations, and accountability to minority shareholders. Those disciplines are not bureaucratic burdens. They are the infrastructure of trust.
What must be done from the Tinubu administration to sustain both the economic and market momentum?
The first requirement is policy consistency, understood not as stubbornness but as predictable governance. Reforms should be evaluated honestly, adjusted where evidence demands it, and protected from arbitrary reversals. Policy stability is strongest when it is supported by transparent rules and institutions rather than by personal assurances.
The second requirement is deeper liquidity. The market needs more market makers, more institutional participation, more credible research, more investable products, and more large-cap issuers. Pension funds and insurance companies can contribute significant patient capital, but the regulatory framework must balance development objectives with fiduciary responsibility. Encouraging equity investment is not the same as compelling it.
The third requirement is investor protection. The SEC, NGX, NGX Regulation, and market-infrastructure institutions must maintain high standards of enforcement, disclosure, settlement, and corporate governance. A market cannot become globally investable if minority shareholders do not trust the quality and timeliness of information.
The fourth requirement is social legitimacy. Investors do not allocate capital to statistics; they allocate capital to economies populated by people, firms, institutions, and consumers. Reforms must therefore be judged by whether they improve productivity and opportunity, not only by whether they produce a stronger index in a particular year.
Higher crude prices, driven by volatile geopolitics, have boosted government revenues and corporate profitability in the energy sector. Do you see this rally sustaining in the long run?
Higher oil prices can support Nigeria’s fiscal revenues, foreign-exchange availability, and energy-sector earnings. A prolonged oil-price decline would create pressure through the budget, the external account, the currency, and investor sentiment. That vulnerability remains real.
Yet Nigeria’s long-term market story cannot be an oil-price story alone. The sustainable objective is to use periods of favourable commodity income to build non-oil productive capacity, improve tax administration, strengthen infrastructure, and invest in human capital. The IMF projects continued growth in both oil and non-oil activity while identifying fiscal, external, security, and social risks that must be managed.
Diversification is not a slogan. It means that more Nigerian firms should earn revenue from manufacturing, food processing, improved mining investment climate, solid minerals processing/value addition, services, technology, logistics, healthcare, and regional trade. It means that the capital market should finance those firms transparently and at a cost that rewards discipline.