Thursday, September 24, 2026
International Finance
CommodityFeatured

China’s gold rush gathers pace as imports top 1,000 tonnes in eight months

IFM_China
Investment demand, central-bank buying and weaker domestic alternatives are driving a surge in Chinese bullion purchases
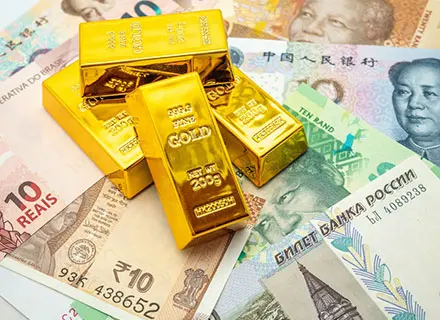
China’s gold imports have surged past 1,000 tonnes in the first eight months of 2026, putting the world’s biggest gold-consuming market on course for another record year as investors, banks and the central bank increase their exposure to bullion.

China spent about USD 158.8 billion on gold imports during the first eight months of the year, already well above the USD 96.5 billion spent on 886 tonnes during the whole of 2025, according to data reported by the Financial Times.

The volume imported through August was the highest for the period since comparable customs records began in 2017.

The surge highlights the strength of investment demand even as high prices have weighed on jewellery consumption.

Gold has increasingly been used by Chinese investors as a store of value amid weakness in property, subdued returns from conventional investments and uncertainty over the domestic and global economic outlook.

China imported 864.95 tonnes in the first half of 2026, an 89.1% increase from 457.39 tonnes in the same period a year earlier, according to customs data. June imports alone reached 173.34 tonnes, their highest monthly level since March 2024.

The pace subsequently moderated. The World Gold Council said China recorded 118 tonnes of net gold imports in July, down 34 tonnes from June but still 34% higher than a year earlier.

The council attributed the year-on-year increase partly to a higher local gold-price premium and continuing strength in bullion investment demand.

Investor demand has been particularly significant. China remains the world’s largest market for gold bars and coins, with demand reaching 314 tonnes in the first half of 2026, the strongest first-half performance on record, according to the World Gold Council (WGC).

Second-quarter demand was 107 tonnes, following an exceptional 207 tonnes in the first quarter.

Gold-backed exchange-traded funds have also attracted substantial money. Chinese gold ETFs added 11 tonnes in August, taking collective holdings to 293 tonnes.

Their assets under management rose by RMB10 billion (USD 1.5 billion) during the month to RMB282 billion (USD 42 billion). In early September, investors continued adding to the funds as domestic bond yields fell and equities remained sluggish.

The strength of investment demand contrasts with softer physical consumption in the jewellery sector. Gold withdrawals from the Shanghai Gold Exchange fell 22% month-on-month and 27% year-on-year in August to 62 tonnes, the World Gold Council (WGC) reported.

High prices, an additional value-added tax burden and a shift towards lighter jewellery products have constrained jewellery demand.

China’s central bank is adding another layer of support. The People’s Bank of China reported a 20.2-tonne increase in its gold reserves in August, its biggest monthly purchase since October 2023.

The move extended its buying streak to 22 consecutive months, taking official holdings to 2,387 tonnes, equivalent to about 9% of its foreign-exchange reserves.

That buying forms part of a broader effort to diversify reserves.

China has been steadily increasing its gold holdings while reducing its exposure to US Treasuries, as geopolitical tensions and concerns about the international financial system encourage central banks to hold more assets outside the dollar-based system.
Analysts have also pointed to China’s efforts to strengthen the resilience of its reserves as a longer-term driver of official gold demand.

Currency movements have also helped. A stronger yuan can make dollar-priced bullion cheaper for Chinese buyers, while periods of weakness in international gold prices have encouraged investors to buy on dips.

The World Gold Council said Chinese investment demand remained supported by safe-haven motives, subdued local yields, weakness in the property sector and limited alternative investment opportunities.

The combination of private investment, ETF inflows, commercial purchases and central-bank accumulation is significant for the international gold market.

China’s physical demand can provide support when prices retreat, potentially absorbing additional supply from profit-taking elsewhere.

Yet the import surge should not be interpreted as uniform strength across every part of China’s gold market.

The recent fall in Shanghai Gold Exchange withdrawals shows that high prices can discourage physical consumption, particularly jewellery purchases.

For global bullion traders, the key question is whether China’s investment appetite remains strong enough to offset price-sensitive demand.

So far, the data point to sustained interest in gold as a portfolio diversifier and store of value, keeping China at the centre of the global bullion market.

What's New

UAE’s Eagle Hills signs USD 12 billion ‘Maldives Waterfront and Marina’ deal

International Finance Business Desk

A team achievement: Almamoon earns global recognition for health insurance innovation

International Finance Business Desk

At 11.4%, Morgan Stanley continues to face elevated private credit redemption requests

International Finance Business Desk

Leave a Comment

* By using this form you agree with the storage and handling of your data by this website.